How to protect yourself against the risks of buy-to-let investment?
Among the various ways to build wealth, real estate is still seen as a safe haven compared to the risks involved in financial investments such as stocks. Investing in property to rent it out is an effective way to build
Among the various ways to build wealth, real estate is still seen as a safe haven, compared to the risks involved in financial investments in the stock market particularly. Investing in property to put the real estate property up for rent is an effective way to build heritage at reduced cost, or to invest existing capital so that it yields a sustainable income while gaining in value.
However, the transaction is not without its risks for all that, and it is wise to protect yourself to preserve not only the investment profitability, but also your financial health and daily peace of mind. Let us detail how to best protect your position when undertaking a buy-to-let investment.
Solutions against unpaid rent
The fear of every landlord is to discover one morning that the rent has not been paid. It should be noted that payment delays can occur and that, particularly in this period of soaring inflation, showing flexibility is advisable if you are not in dire straits. When we speak here of unpaid rent, we are assuming that the tenant has not paid at least two consecutive monthly instalments and is not reassuring regarding the settlement of what is owed. Delays can also accumulate, putting you in a difficult situation with your own bank for the repayment of the mortgage, where applicable.
The first good reflex is to maintain dialogue with the tenant, to prevent the situation from deteriorating – and to determine whether an amicable solution can be found or not. In any case, certain precautions can contribute to ensuring your financial peace of mind.
Selecting the tenant carefully
First and foremost, you should not have just anyone sign a lease. A careful study of the candidate tenant’s file should be carried out, to verify that they positively answer the following questions:
- Do they have sufficient and regular financial resources, to comfortably afford the rent and charges?
- Is their situation eligible for the guarantees you wish to take out?
- Are the supporting documents presented genuine?
A relationship of trust should be able to form from the first exchanges, and you can otherwise trust your instinct. It is better to take time to find the right tenant, than to rent quickly to a tenant who is a bad payer!
Requiring a guarantor
As a third party committing to pay the rent in the event of difficulty for the tenant, the presence of a physical guarantor is reassuring. The guarantor can be a “simple” guarantee, and you will then be able to contact them after first following up with the tenant and if they do not settle the situation. In a second case, the “joint and several” guarantor must cover the tenant’s payment default as soon as it appears.
In all cases, the guarantor commits to paying what is set out in the guarantee agreement you have had them sign, in the event of the tenant’s default: the rent of course, but also the charges, taxes, maintenance of the property, etc.
Unfortunately, the guarantor precaution may not be sufficient, if they also become insolvent or refuse to intervene. The recovery procedure or eviction proceedings that are then initiated will undoubtedly prove lengthy and costly, including morally.
Protecting yourself with Unpaid Rent Guarantee (GLI)
It will only be accessible if you present a solvent tenant with a secure situation: a permanent employment contract, income of at least 3 times the rent amount and no history of unpaid rent. Various documents will be requested from them to justify this, and if accepted, you may be compensated for:
- Any unpaid rent, up to the date of their voluntary or forced departure;
- Any damage noted on the inventory of fixtures at departure, as well as for the loss of rent caused by the delay in restoring the property (to be taken out as an option);
- The loss of rent suffered if the tenant suddenly abandons the property or passes away;
- The procedure costs inherent to an eviction request or recovery action.
Other insurance policies besides the GLI exist to protect against the risk of non-payment; in any case, be sure to carefully study the proposed contract: cost, excess or restrictions on the choice of tenant could surprise you.
Preventing financial loss through the Visale scheme
This is a guarantee granted by Action Logement under certain conditions, intended to compensate a landlord for lost rent and charges, to the amount of the debt. The organisation will then turn against the defaulting tenant.
A limit is set at 36 monthly instalments, and the rent must not exceed – charges included – €1,500 in Paris, or €1,300 in the provinces. As for damage affecting the property, it may be subject to compensation of up to 2 months’ rent.
Keeping your property in good condition
This is an essential point, which if poorly managed, can strongly impact the intrinsic value of the property or generate substantial renovation costs. A prudent owner will pay particular attention to protecting themselves against damage that tenants might cause. We mentioned earlier the guarantee against damage that can be taken out with the GLI, but other steps are necessary here.
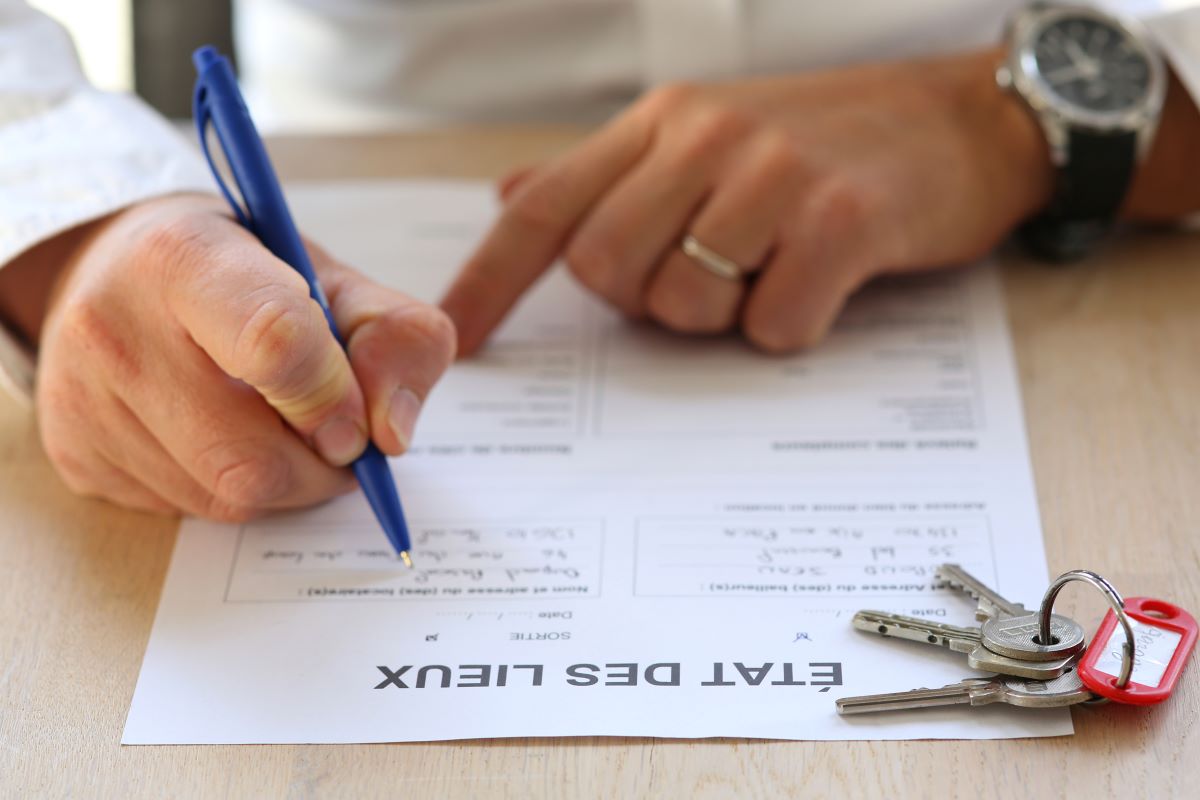
Carrying out a detailed inventory of fixtures
This is a step that may seem fiddly and time-consuming, which the law does not otherwise require, but which you will be glad to have carried out if there is a problem.
Do not hesitate to draw up a document to list, for each room, the various elements present, with a view to reaching agreement with the tenant on their condition. This may concern the walls and floors, but also the switches, plumbing, kitchen and sanitary equipment, or even the seals and other specific details. You can then create an analysis grid allowing you to quickly indicate, using simple crosses for each element, whether the condition is new, acceptable or degraded.
By signing such a document, the tenant cannot act in bad faith during the inventory of fixtures at departure. To ensure you are reimbursed for damage, you can rely on the deposit taken at the start of the tenancy – also called the security deposit.
Being reimbursed for minor damage through the security deposit
Automatically payable when entering into the lease, the security deposit is equal to one month’s rent excluding charges. It may be paid directly by the tenant, by the loca-pass advance from Action Logement or by the housing solidarity fund (FSL).
You will be entitled to decide what to do with this sum when the tenant leaves, and therefore retain all or part of it if you consider it necessary for returning the property to its original condition. This assessment remains subjective and is often the subject of negotiation between the tenant and their landlord.
Insuring your property in your absence
Damage is not always the fault of the tenant, and can occur when the property is empty: fire, flooding, vandalism, are all risks that should be covered. If the property is unoccupied therefore, take out non-occupier landlord insurance which will cover the costs depending on the options chosen. These may include covering mortgage instalments, repairing damage, or even reimbursing objects or equipment present in the property.
If you own unoccupied property within a co-ownership, the ALUR law actually requires you to take out such insurance. Be careful, a failure could have serious consequences in the event of a claim affecting other properties in the co-ownership.
Preventing the risk of vacancy
An empty property represents a cost – or absence of earnings – that can quickly become problematic. Vacancy can occur and persist if certain precautions are not taken at the time of purchase or during the rental life of the property.
Targeting the right location
A property may be exceptional in its intrinsic characteristics, yet it will not interest any tenant if it is located in the middle of an isolated forest. Finding demand to match your offer requires an attractive geographical position: in the town centre, close to shops and schools, cultural venues or within developing neighbourhoods. This is the first criterion to study, notably with a view to selecting a search area where properties can be presented at a price matching your budget.
Making your property suitable for letting
An investor is sometimes tempted to acquire a cheap property but in doubtful condition, to maximise the immediate profitability of their investment. In such a case, it is essential to ensure that the property meets the basic criteria for letting and notably, that the decency criteria set by law are properly met.
Given the strong rental competition in certain areas, it may prove useful to go further and carry out partial or total renovation of the acquired property. If the initial financial burden increases, the landlord may benefit by noticeably increasing the rent and ultimately by having a higher property value on the market.
During such work, be careful to really think about the layout and equipment according to today’s households’ expectations: a spacious living room, a nice open kitchen, a wood-fired heating system, are all assets that will ensure permanent occupancy of the property.
Finally, when each tenant leaves, do not hesitate to take stock to return the property to a good condition, or even improve it, to relet it as quickly as possible.
Setting a reasonable rent
Outside of areas where rent is regulated, you might be tempted to increase your monthly earnings. This can be a bad idea if competition is fierce: potential tenants will flee your property. Observe the market and set an affordable rent. This particular point should guide your financial structure and not the other way round: do not seek to make your investment profitable through an inflated rent, rather aim for a property whose natural rent makes your structure profitable.
Pampering the tenant in place
Finally, retaining the occupant of your property will obviously reduce the risk of rental vacancy. Ensure you maintain good relations, be responsive in the event of a request from them and do not hesitate to regularly propose improvements to the property, by replacing or modernising equipment, renovating the paint or floors, in short: by carrying out the work that you would in any case have done well after their departure!
Investing more serenely thanks to LMNP
To conclude, note that there is a way of investing through which most risks linked to buy-to-let investment disappear: furnished letting (LMNP).
By investing under this status in a serviced residence, you entrust the management responsibility to the residence operator: they will be responsible for finding a tenant, for rent recovery, for managing and offsetting any damage at their expense. The contract signed at the outset even commits them to paying you the planned rent, when the property remains unoccupied!
The LMNP status also allows you to receive income which will be taxed as trading profits (BIC) and not as property income: this will cost you less in taxes.
Investing serenely requires paying particular attention to the initial financial structure, and covering yourself with certain specific precautions. One final useful piece of advice: when choosing the property, be careful not to invest emotionally. You are then in the skin of an investor, you are not buying the property to live in. Therefore, do not look for a property in which you feel comfortable, but rather a property that objectively meets the criteria you will have set with a view to letting it. Good hunting!


